
October has a way of making your wallet nervous.
Festivals are coming. There are sales everywhere. New clothes suddenly seem necessary, your wishlist somehow doubles overnight, and every shopping app starts behaving like it knows exactly when you got paid.
And honestly, there is nothing wrong with spending money during the festive season.
The problem starts when October spending becomes November’s financial headache.
This year, festive shoppers are already becoming more careful about where their money goes. A 2026 YouGov festive-shopping report found that many Indian consumers are keeping their budgets but becoming more selective about what they buy, with quality and price among the biggest considerations.
So before the big sales and festive shopping properly kick in, take 30 minutes and do an October money reset.
You don’t need a complicated spreadsheet.
Just check these 10 things.
1. Check how much money you actually have
Start with the most obvious thing — and somehow the thing many of us avoid.
Open your bank account and check:
- Current balance
- Money expected this month
- Upcoming bills
- EMIs
- Credit-card dues
- Subscriptions
- Any pending payments
Don’t calculate your festive-shopping budget based on your bank balance.
Calculate it based on what remains after your important expenses.
For example:
Money available: ₹50,000
Bills + EMI: ₹20,000
Essential spending: ₹15,000
Savings: ₹5,000
That leaves:
₹10,000 for flexible spending
That ₹10,000 is your actual starting point — not ₹50,000.
It sounds simple, but this one calculation can stop a lot of “I’ll figure it out next month” spending.
2. Make a festive shopping budget before opening a sale app
This is important because shopping platforms are designed to make you keep browsing.
And browsing becomes:
“It’s only ₹799.”
Then another ₹1,299.
Then ₹499.
And suddenly you’ve spent ₹8,000 on things you didn’t even know existed yesterday.
Before the sale begins, decide how much you are comfortable spending.
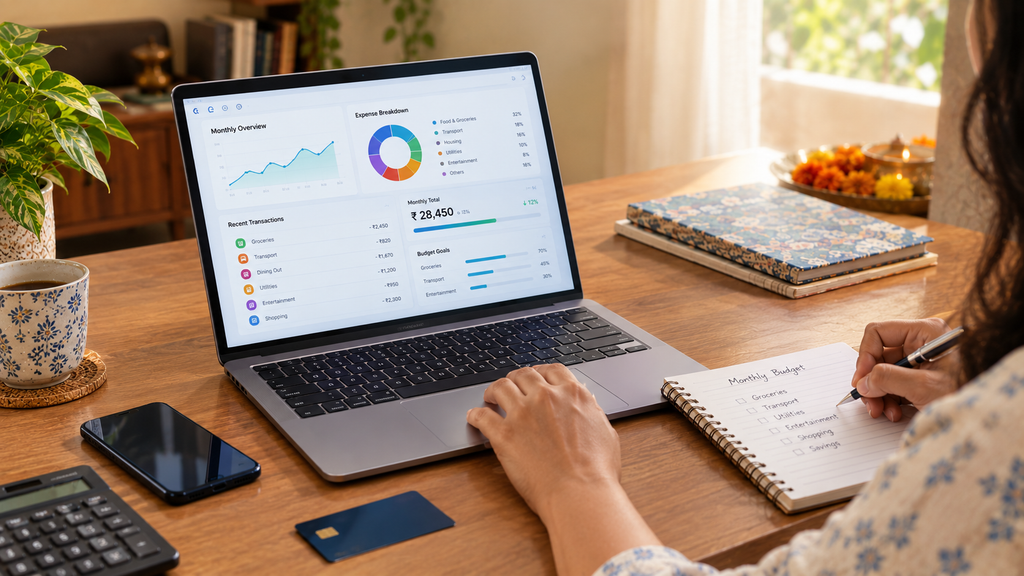
You can divide the amount into categories:
| Category | Budget |
|---|---|
| Clothes | ₹____ |
| Gifts | ₹____ |
| Home | ₹____ |
| Travel | ₹____ |
| Food/celebrations | ₹____ |
| Personal shopping | ₹____ |
| Other | ₹____ |
The exact amount will obviously be different for everyone.
The point is to give your money a job before the shopping starts.
Amazon’s Great Indian Festival 2026 begins on October 8 for all customers, with offers across electronics, fashion, beauty, home and other categories. Amazon is also advertising additional payment-related offers during the sale.
That makes having your budget ready before the sale even more useful.
3. Check your credit-card outstanding amount
If you use a credit card, October is a good time to check the complete picture.
Don’t look only at:
“Available credit: ₹80,000.”
Look at:
- Current outstanding
- Statement balance
- Minimum amount due
- Payment due date
- Existing EMIs
- Recent large purchases
And most importantly:
Can you pay the full statement amount?
If yes, great.
If you’re regularly carrying a balance forward, be much more careful about adding festive purchases to it.
A discount doesn’t automatically make something affordable.
A ₹5,000 purchase is still ₹5,000 even if the app says:
“20% OFF 🔥”
4. Look at your EMIs before taking another one
Festive sales make EMI options look very harmless.
Sometimes the product page barely shows the total price.
Instead, it highlights:
₹2,499/month
And suddenly the ₹30,000 purchase feels smaller.
Before choosing EMI, calculate the complete commitment.
Ask yourself:
How much will I pay in total?
How many months will I be paying?
Are there processing fees or other charges?
Will this EMI overlap with my existing EMIs?
And:
Do I actually need the product right now?
The monetary policy decisions can eventually influence borrowing and deposit rates, although changes don’t automatically pass through to every loan or deposit at the same time or by the same amount.
Better anchor: RBI MPC October 2026
So if you already have loans, keeping your monthly obligations under control matters even more than finding one extra festive discount.
5. Check your subscriptions
This one is boring.
It is also surprisingly useful.
Open your bank statement or payment history and look for recurring payments.
Maybe you’re paying for:
- Streaming services
- Cloud storage
- Apps
- Software
- Fitness memberships
- Music subscriptions
- Gaming services
- Shopping memberships
Now ask:
Did I actually use this last month?
If the answer is no, cancel it.
You don’t need to cancel everything fun.
The idea is simply to stop paying for things you forgot you were paying for.
Even ₹199 here and ₹299 there can quietly become several thousand rupees a year.
6. Check your emergency savings before spending on wants
Festive shopping should come after your basic financial safety net, not before it.
If you have emergency savings, check:
How many months of essential expenses could this cover?
If you don’t have much emergency savings yet, October may be a better month to strengthen that first rather than spending your entire surplus on shopping.
For example, if you have ₹20,000 extra available, you don’t automatically need to spend all ₹20,000 because it’s festival season.
You could decide:
₹10,000 → savings
₹5,000 → festive spending
₹5,000 → future expenses
Your numbers will be different.
The principle is what matters:
Don’t let festive spending consume every rupee you have available.
7. Review your investments — but don’t make impulsive changes
If you invest regularly, October is a good time to check whether your current contributions still fit your financial situation.
You can review:
- SIPs
- Mutual funds
- PPF
- NPS
- Fixed deposits
- Other investments
But there is an important difference between reviewing and randomly changing investments because you need shopping money.
If you need money for a purchase, first look at your actual cash flow and budget.
Don’t automatically stop long-term investments every time a sale appears.
And don’t start a new investment simply because someone on social media says:
“This is the next multibagger.”
For investment decisions, understand the product, risk, time horizon and costs before putting money into it.
8. Make a “Want vs Need” list
This might sound like the most basic advice ever.
But it works.
Before buying something, put it into one of these three categories:
NEED
Something you genuinely need.
Example:
Your laptop is broken and you need one for work.
REPLACEMENT
Something you already own but genuinely need to replace.
Example:
Your old phone battery has become unreliable and the device is no longer practical for your needs.
WANT
Something you simply like.
And that’s okay too.
You are allowed to buy things because they make you happy.
Just know which category you’re spending from.
The problem isn’t buying a ₹2,000 outfit because you love it.
The problem is convincing yourself that every ₹2,000 outfit is somehow an essential expense.
9. Don’t assume “sale price” means “best price”
This is particularly important during festive shopping.
A product can be advertised as:
₹9,999 → ₹5,999
and still not necessarily be the best deal available.
Before buying expensive products, compare:
- Price across retailers
- Previous selling price
- Warranty
- Seller rating
- Return policy
- Included accessories
- Delivery charges
- Payment discounts
If you want to use AI to make this process faster, check out our guide on THIS, where we explain how AI can help compare products, understand reviews and shop more carefully.
For electronics and appliances especially, don’t compare only the headline discount.
Compare the final amount you’ll actually pay.
And if you’re buying something expensive, give yourself a cooling-off period.
If you still want it tomorrow, consider it again.
10. Set one financial goal for November
This is the part people usually skip.
They finish October.
They survive the shopping.
Then November begins.
And they’re back to:
“Okay… where did my money go?”
Instead, decide your November target now.
It could be:
- Save ₹10,000
- Clear one credit-card balance
- Reduce one EMI
- Build an emergency fund
- Stop unnecessary subscriptions
- Start a monthly budget
- Increase your savings contribution
- Pay an outstanding bill
Keep it simple.
One clear target is better than creating a 17-step financial transformation plan that you’ll abandon after four days.
Your 30-Minute October Money Reset
If you don’t know where to start, do this today.
First 5 minutes
Check:
Bank balance + cash available
Next 5 minutes
Write down:
Bills + EMIs + credit-card dues
Next 5 minutes
Check:
Subscriptions + recurring payments
Next 5 minutes
Decide:
Festive shopping budget
Next 5 minutes
Check:
Savings + investments
Final 5 minutes
Write:
My November money goal: __________
That’s it.
You don’t need a fancy finance app.
You just need to know where your money is going.
A Simple Festive Shopping Rule
Here’s a rule you can actually remember:
Don’t buy something just because it’s discounted.
Buy it because:
You wanted it + you can afford it + the price is genuinely good + it doesn’t mess up your other financial priorities.
All four matter.
A 50% discount on something you don’t need is still 100% unnecessary spending.
What About UPI, Cards and EMI Offers?
This is where festive shopping can get confusing.
Different payment methods may come with different offers, cashback, discounts or fees.
So before choosing a payment method, check the actual terms.
Don’t assume:
Credit card = cheaper
or
UPI = cheaper
or
EMI = cheaper
The best payment method depends on the specific transaction and your ability to pay it back.
Also remember that payment-related rules can change. October 2026 itself has several financial changes and policy developments, so consumers should check current bank/payment-provider terms rather than relying on old screenshots or social-media posts.
The October Money Reset Checklist
Save this somewhere:
☐ Check bank balances
☐ List all upcoming bills
☐ Check EMI commitments
☐ Check credit-card outstanding
☐ Cancel unused subscriptions
☐ Check emergency savings
☐ Review regular investments
☐ Set a festive shopping budget
☐ Compare prices before expensive purchases
☐ Decide your November financial goal
And that’s your October money reset.
You don’t need to stop enjoying the festive season.
You just need to make sure November-you doesn’t hate October-you.
FAQs
How much should I budget for festive shopping?
There isn’t one percentage that works for everyone. Start with the money left after essential expenses, debt payments and your planned savings. Then decide what portion you’re comfortable spending.
Should I use a credit card for festive shopping?
A credit card can be convenient and may offer rewards or discounts, but only use it if you can manage the repayment responsibly. Check the full statement balance and payment terms before spending.
I